October 29, 2026 | Real Estate News
Bank of Canada Rate Hike: What the Move to 2.5% Means for You
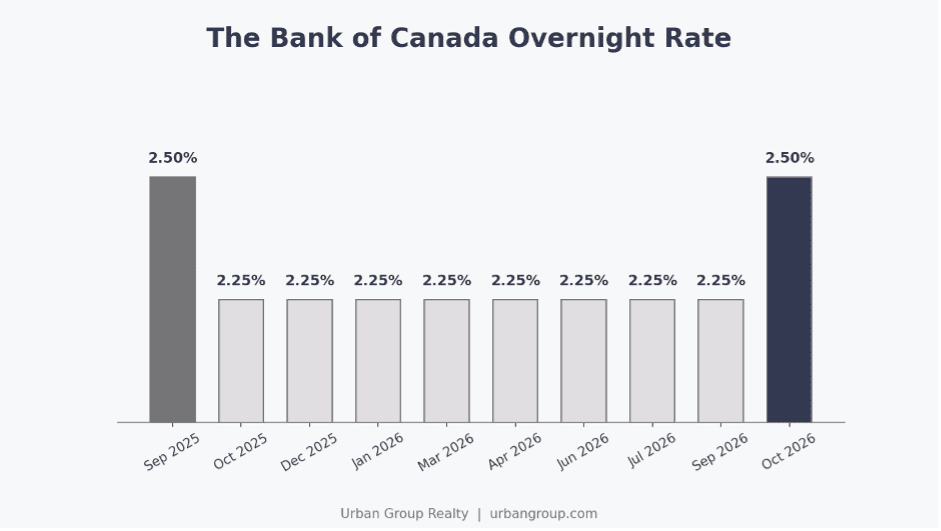
The Bank of Canada raised its key interest rate today. The quarter point hike brings the overnight rate to 2.5%, up from 2.25%.
This is the first hike since July 2023. It also ends a year of steady holds. For homeowners and buyers in Burlington, Oakville, and Hamilton, the news raises a simple question. What does this hike mean for me?
Here is a clear look at what changed, why it happened, and how it may affect your plans.
What Changed With This Hike
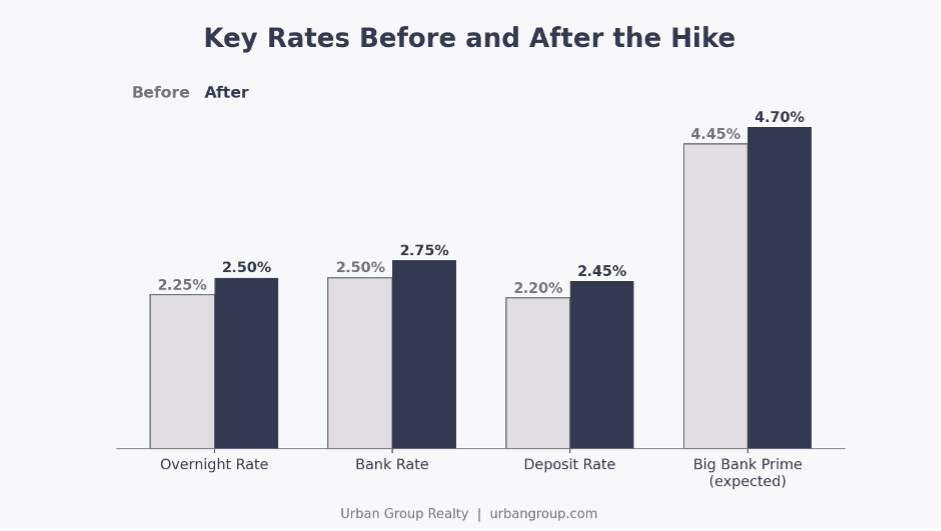
On October 28, the Bank of Canada increased its overnight rate by 25 basis points. The Bank Rate now sits at 2.75%, and the deposit rate is 2.45%.
The rate had stayed at 2.25% since October 2025. Over that time, the Bank held steady at seven straight announcements. As a result, many Canadians grew used to stable borrowing costs.
Markets largely saw this hike coming. In fact, a Reuters poll found most economists expected a quarter point increase. Even so, the move marks a real shift in direction.
Why the Bank of Canada Chose a Hike
The main reason is inflation. Energy prices have climbed, and the Bank wants to stop them from spreading to everyday goods and services.
Governor Tiff Macklem said the hike was needed to reduce the risk of broader inflation. September inflation came in at 3.1%, above the Bank’s 2.0% target.
The Bank also raised its 2027 inflation forecast to 3.1%. In July, it expected just 2.0%. That jump explains much of today’s decision.
Meanwhile, the economy has shown some resilience. The Bank expects growth of about 1.0% this year and 2.0% in 2027. However, it also noted that trade tensions keep the outlook uncertain.
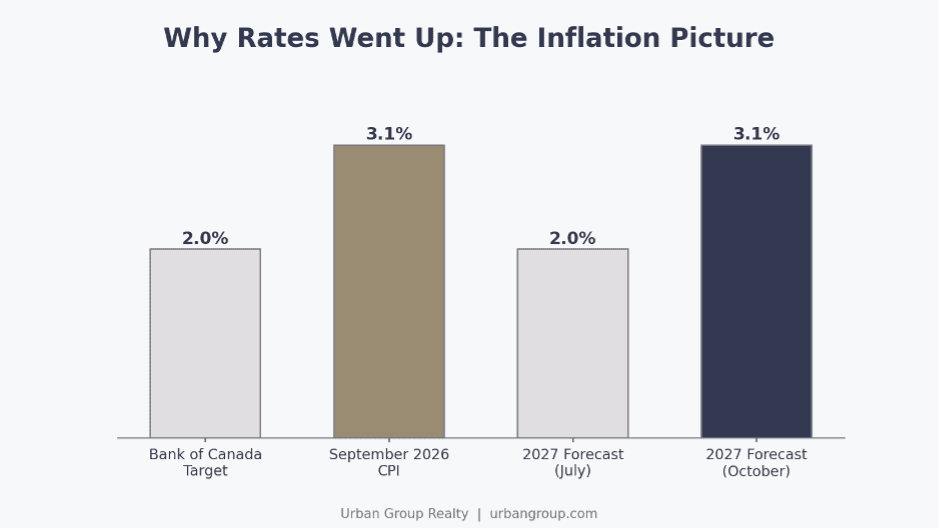
How the Hike Affects Variable Rate Mortgages
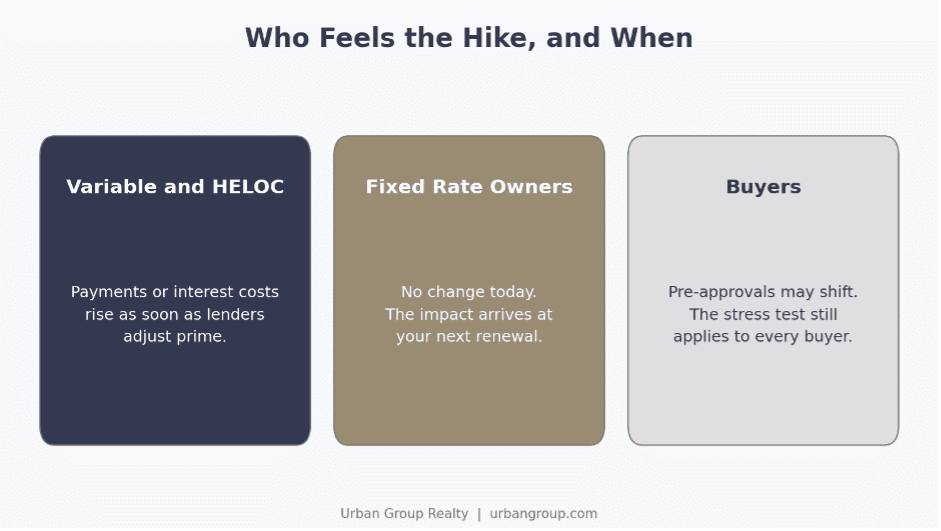
Variable rate mortgages and home equity lines of credit follow the prime rate. Prime at the big banks has been 4.45%. After a hike like this one, lenders usually raise prime by the same amount, which would bring it to about 4.70%.
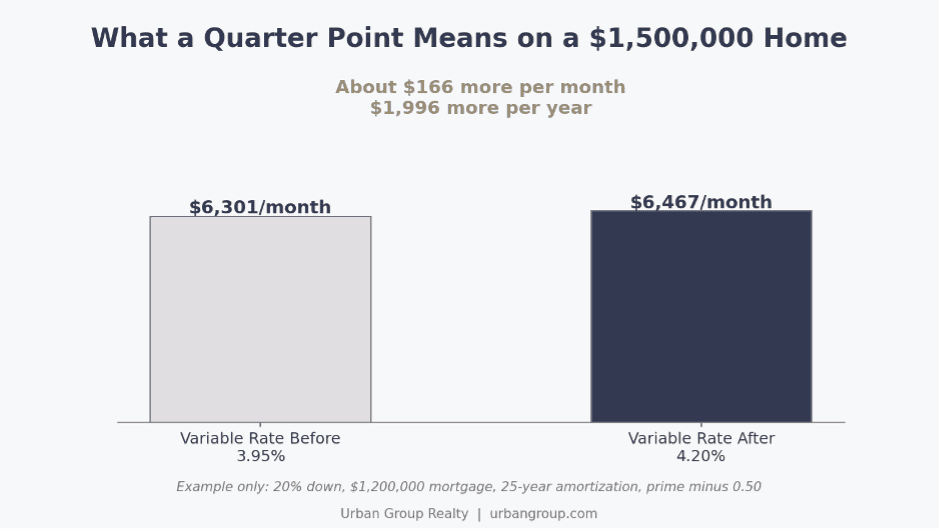
So what does that look like in real dollars? Consider a $1,500,000 home in Halton with 20% down. That leaves a $1,200,000 mortgage on a 25-year amortization.
At a variable rate of 3.95%, the monthly payment is about $6,301. After the hike, at 4.20%, it rises to about $6,467. That is roughly $166 more each month, or close to $2,000 per year.
Your numbers will differ based on your lender, discount, and payment type. Some variable mortgages have fixed payments. In that case, more of each payment goes to interest instead of principal.
What the Hike Means for Fixed Rate Owners
If you have a fixed rate mortgage, your payment does not change today. Your rate is locked until the end of your term.
However, fixed rates had already been rising this fall. Fixed rates follow bond yields rather than the Bank of Canada directly. Several big banks raised select fixed rates in September and October.
If your renewal is coming up in the next year, now is a good time to plan. Talk to your mortgage professional early. That way, you can compare options before your renewal date arrives.
What the Hike Means for Buyers
For buyers, a higher rate can lower the amount you qualify for. Every buyer must still pass the mortgage stress test. That means qualifying at the higher of 5.25% or your contract rate plus 2%.
Still, a single quarter point hike is a modest change. Rates remain below the levels seen in 2023 and early 2024. Also, the Bank says its rate is still below neutral, which means it is not yet slowing the economy.
If you already hold a pre-approval, check in with your lender. Many pre-approvals lock a rate for a set period. That protection could work in your favour right now.
What the Hike Means for Sellers
Sellers in Burlington, Oakville, and Hamilton should not panic. Local demand is driven by more than rates. Space, schools, commute, and lifestyle still matter to buyers.
That said, pricing matters more than ever after a hike. Buyers may be more careful with budgets. A well-priced, well-prepared home will continue to stand out.
If you are thinking about listing, a current market evaluation can help. It shows where your home fits today, not where it fit last spring.
Could Another Hike Follow?
The Bank signalled that more increases could come if inflation stays high. Economists polled by Reuters expect one more hike by the end of March.
The next Bank of Canada announcement is on December 9. We will share an update right after that decision.
In the meantime, the best move is to stay informed and plan ahead. Small adjustments today can make a big difference later.
Navigating the Hike With Urban Group Realty
Rate changes can feel stressful. You do not have to sort through them alone. Our team tracks every Bank of Canada decision and what it means for our local market.
Whether you are buying, selling, or renewing, we are here to help you make a confident decision. Visit urbangroup.com or call 905.673.1032 to connect with our team.
Frequently Asked Questions
The Bank of Canada announced a quarter point hike, raising its overnight rate from 2.25% to 2.5%. It is the first increase since July 2023.
The Bank wants to keep higher energy prices from spreading into broader inflation. It also raised its 2027 inflation forecast to 3.1%.
If you have a variable rate mortgage or a line of credit, your costs will likely rise once lenders adjust prime. Fixed rate payments stay the same until renewal.
On a $1,200,000 variable mortgage with a 25-year amortization, the hike adds roughly $166 per month. Your exact amount depends on your lender and mortgage terms.
For many buyers, yes. A single hike is a modest change, and rates remain below recent highs. Speak with your agent and lender about your personal situation.
The next announcement is scheduled for December 9, 2026.
You May Also Like
- How Interest Rate Shifts Affect Your Property Value
- Bank of Canada Rate Reduction and Its Impact on the Real Estate Market
- How to Price Your South Burlington Home for a Quick Sale
- Burlington Market Update: July 2026
Get The Newsletter
Join our mailing list to get updates from our experts about the Toronto market, the latest listings, and our industry insights.